One metric explains this market better than any other: about 30 rounds this year against 28 in all of 2025. Deal count barely budged. The money went up fourfold anyway.
Construction and robotics companies pulled in roughly $1.6B through Oct 29, versus $389M across the whole of last year and a prior peak of $506M in 2021, per Crunchbase data. Contractors cannot hire enough skilled tradespeople, projects run late because of it, and the data centre construction wave is competing for the same crews.
Three companies carry the total
Concentration, not breadth, produced the number. Bedrock Robotics supplied $870M of it across a February Series B worth $270M and an October Series C worth $600M led by CapitalG and Emergence Capital, at a $4.1B valuation for a company founded two years ago.
Icon, the Austin home printer, added $265M through a $65M March round and a $200M October Series D led by Baillie Gifford and BlackRock. Gravis Robotics took another $200M. Icon has raised close to $800M since 2017 and delivered more than 270 homes and structures in five states and two countries.
The question changed
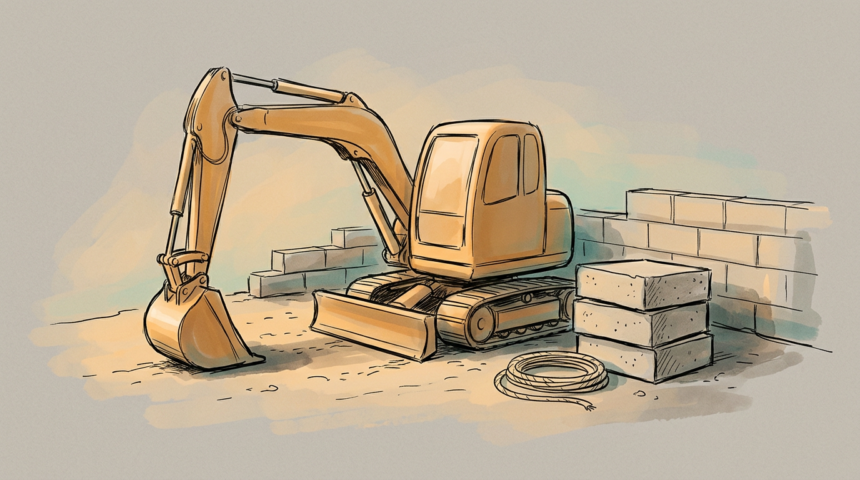
Bedrock retrofits existing heavy plant into autonomous machines; its excavators have been running without operators on commercial jobs in Texas and Nevada. Buyers have stopped asking whether a robot can build and started asking whether a supplier can deliver across geographies and improve unit economics on each build.
A handful of mega-cheques can flatter a sector statistic for a year. Repeat deployments across many sites cannot.